Strategic Trade and International Finance Monitor
Last reviewed:
Updates since publication
- USMCA. At the USMCA joint review on July 1, 2026, the United States did not agree to renew the agreement in its current form. USTR says the agreement remains in force while the review continues. This article was written in January 2026, before the review. On October 2, 2026, USTR opened a public consultation ahead of the 2027 joint review; written comments are due January 12, 2027.
Strategic Trade and International Finance Monitor: Global Economic Statecraft and the Small Business Landscape
In the opening weeks of 2026, the global trading architecture is undergoing a structural transformation that matters to small businesses that trade across the hemisphere. U.S. trade policy is moving away from the "rules-based order" toward "managed volatility" and "economic statecraft." For clients of Gestión Orbis, these legislative and executive actions from Washington are no longer background noise—they are active disruptors of supply chains and market access.
For a practical compliance reference (in Spanish), see our U.S. Import Compliance Guide (2026) and the Incoterms 2020 Guide and Calculator.
This monitor analyzes four critical developments from the Congressional Research Service (CRS) that define this shift: the escalation of the US-Canada lumber dispute, the looming USMCA review, the financial pivot to Argentina, and the intervention in Venezuela.
1. The North American Fracture: Lumber & The USMCA
The Recrudescence of the Lumber Wars
The U.S.-Canada softwood lumber dispute has metastasized. Since 14 October 2025 a 10 percent Section 232 national-security tariff has applied to softwood timber and lumber imports, on top of antidumping and countervailing duties that the U.S. Commerce Department cut in October 2026 to a combined 24.75 percent for most Canadian producers, down from about 35 percent (Global Affairs Canada). This creates immediate "political risk premiums" for construction sectors in Florida, Georgia, and Alabama.
For our clients in the Southeastern construction market, relying on stable material costs is no longer feasible without hedging. We recommend engaging with regional suppliers who may offer alternative sourcing or distinct supply chain advantages. Companies like West Fraser Timber Co. (with significant operations in the South) and Rex Lumber (operating in Florida, Georgia, and Alabama) are among the companies to watch as U.S. mills try to replace Canadian imports.
The USMCA Joint Review Crisis
The USMCA joint review was set for July 2026 (see the update above). Friction points regarding automotive Rules of Origin and energy policy threaten to destabilize the North American trading bloc.
Automotive suppliers in the "Southern Auto Corridor"—such as those supplying Hyundai Motor Manufacturing Alabama and Mercedes-Benz U.S. International—must conduct immediate supply chain audits. Ensuring compliance with Regional Value Content requirements is essential to avoid potential tariff penalties if the agreement's terms are renegotiated aggressively.
2. Hemispheric Finance: The Argentina Pivot
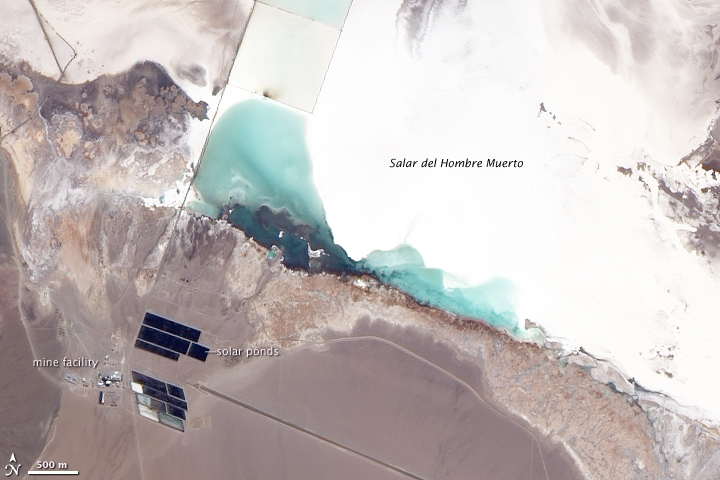
The U.S. has extended significant financial support to Argentina via the Exchange Stabilization Fund (ESF). This strategy is dual-purpose: stabilizing the Milei administration and securing access to the "Lithium Triangle" to counter Chinese influence.
While this opens opportunities for U.S. mining and tech sectors, it presents a competitive threat to American agriculture. A stabilized Argentine peso lowers export transaction costs for their soy, corn and wheat sectors. Agricultural exporters in the Southeast, represented by groups like the Georgia Soybean Commodity Commission, should monitor global price depressions as Argentine commodities re-enter the market at scale.
3. The Venezuela Intervention & Energy Reconstruction
When this was written in January 2026, U.S. policy toward Venezuela was shifting from sanctions toward reconstruction.
Any reconstruction would draw on Gulf Coast logistics and Oil Field Service (OFS) firms. Companies with strong regional logistics footprints, such as those operating out of the Port of Savannah or the Port of Mobile, as well as energy service giants like Halliburton (active in the Gulf region), could take part.
See also our South America agriculture briefing, updated with USDA’s 2026 Venezuela report.
Strategic Synthesis for SMEs
Small businesses that trade across the hemisphere should plan for resilience, not only efficiency. We recommend monitoring policy analysis from regional experts. The Center for International Business and Economic Development at Troy University and the Business Research Center at Southeastern Louisiana University provide excellent regional economic data that can help navigate these macro-level shifts.
Questions about your market-entry plan?
Orbis Management helps Latin American exporters selling to the U.S., and U.S. businesses entering Latin America, assess markets, partners and incentives. Get in touch to discuss your situation.
Sources and resources referenced in this article
- Global Affairs Canada
- West Fraser Timber Co.
- Rex Lumber
- Hyundai Motor Manufacturing Alabama
- Mercedes-Benz U.S. International
- Georgia Soybean Commodity Commission
- Port of Savannah
- Halliburton
- Center for International Business and Economic Development
- Business Research Center at Southeastern Louisiana University